You are using an outdated browser and your browsing experience will not be optimal. Please update to the latest version of Microsoft Edge, Google Chrome or Mozilla Firefox. Install Microsoft Edge

March 29, 2023

Cambodia Issues Decision on Thresholds for Merger Filings

On March 14, 2023, the Competition Commission of Cambodia (CCC) set out its merger filing thresholds in Decision No. 095 on Thresholds for Prior Notification of Business Mergers. This was a follow-up to the recent issuance of a regulation outlining the requirements and procedures for merger and acquisition filings. Decision No. 095 applies to all business combinations subject to premerger notification requirements under this prior regulation.

The thresholds for when the CCC must be notified of a merger are laid out in the table below.
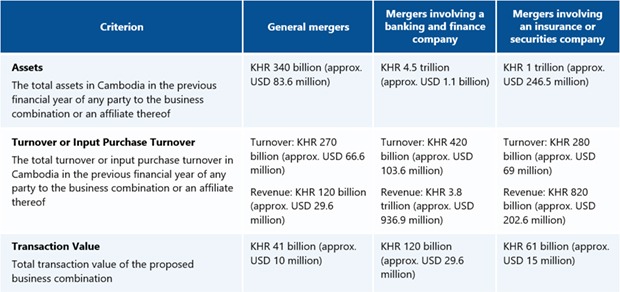
In current practice, the term “turnover” typically refers to a company’s total sales revenue, while “input purchase turnover” denotes the value of materials or equipment acquired for production purposes. Although this reflects the initial interpretation of these terms, it is advisable to seek confirmation or clarification from the CCC before the filing to ensure accuracy and alignment with their current definitions, as it is conceivable that the interpretation may change.

Decision No. 095 leaves room for the Ministry of Commerce to amend these thresholds as deemed necessary.

Outlook

In the last two years, Cambodia has steadily issued regulations to strengthen its legal framework for competition. Although gaps remain, especially with regard to enforcement of fines and certain unclear terms, more regulations are likely in 2025 and 2026.
RELATED INSIGHTS​ 

September 18, 2026
In August 2026, Vietnam’s Ministry of Industry and Trade released a draft decree to replace Decree No. 35/2020/ND-CP detailing certain articles of the Competition Law (Decree 35). The key changes under the draft decree and their implications for M&A transactions in Vietnam are summarized below. Definition of “Management Body” Decree 35 uses the term “management body” (bộ phận điều hành) as one of the criteria to determine the group of affiliated enterprises for the purpose of merger filing. However, there is no definition of the term, leaving enterprises without a basis on which to apply it consistently. The draft decree introduces a statutory definition of “management body,” being a person or group of persons who (i) own more than 50% of charter capital or voting shares; (ii) hold ownership or use rights over more than 50% of an enterprise’s assets; (iii) are an enterprise manager under enterprise law; or (iv) have decision-making power over the enterprise’s resolutions, daily business operations, or business and investment plans. This helps enterprises better assess the scope of merger filing. Determination of Relevant Product Market Under Decree 35, the relevant product market is defined solely by reference to goods and services interchangeable in characteristics, intended use, and price without accommodating digital or zero-price products. The draft decree expands the relevant product market to include “products” (sản phẩm) in addition to traditional “goods and services,” which captures digital information products, AI products, and other novel offerings. Additionally, it adds “other relevant competitive factors” such as quality of products, goods, and services for determining the relevant product market, supplementing the existing factors of characteristics, intended use, and price. This addresses cases where price substitutability is not meaningful for certain consumers or users, i.e., zero-price products. Determination of Relevant Geographic Market Under Decree 35, only physical geographic
September 15, 2026
The Myanmar Investment Commission (MIC) has issued a notification that gives investors with projects in Myanmar clearer guidance for securing approval and for changing, expanding, or exiting an approved project. Issued on August 19, 2026, MIC Notification No. 5/2026 replaces MIC Notification No. 26/2021 and sets procedures for state or regional investment committees to review, approve, and supervise investment projects, including project amendments, investment increases, land-use rights applications, compliance inspections, and suspension or termination of approved businesses. Endorsement Application Timeline and Deemed Acceptance In Myanmar, prospective investors seeking approval under the Myanmar Investment Law generally do so through an MIC permit or an MIC endorsement, depending on the nature of the investment. While certain large-scale investment projects require an MIC permit, projects that are not required to obtain an MIC permit may instead apply for an MIC endorsement. Investors seeking MIC endorsement for their planned projects typically submit their applications to the relevant state or regional investment committee. These committees are established under the Myanmar Investment Law and are authorized to approve investments of less than USD 5 million, subject to the project’s nature and location. MIC Notification No. 5/2026 specifies that upon receiving an endorsement application, the relevant investment committee office will check it for completeness and determine whether it can be considered at the state or regional level or must be referred to the MIC; if it must be forwarded to the MIC, this will be done within 10 working days. If an application is within its purview, the committee may reject the endorsement application within 15 working days of receipt; otherwise, the application is deemed accepted. If approved, the endorsement certificate will be issued within 10 working days of the approval decision, subject to applicable procedures. Endorsement Certificate Amendment The notification clarifies which amendments a state
September 9, 2026
Certain securities, derivatives, and treasury activities in Thailand were opened to foreign investors when Thailand’s Ministry of Commerce published two new ministerial regulations in the Government Gazette on August 28, 2026. The regulations significantly broaden the service activities that foreign-owned businesses may conduct without a license or certificate under the Foreign Business Act B.E. 2542, as amended (FBA). Securities and Derivatives Business Exemptions Prior to the issuance of these ministerial regulations, the exemptions covered (1) securities brokerage and derivatives brokerage with their only underlying assets being agricultural commodities, financial instruments, and securities; and (2) dealers, advisers, and fund managers conducting derivatives business under Thailand’s derivatives laws. The ministerial regulations provide broader exemptions. In addition to derivatives under the laws on derivatives as before, the following two major categories are provided: Derivatives whose underlying assets or variables fall outside the scope of Thailand’s laws on derivatives. This addresses a gap in the previous framework, which did not comprehensively exempt derivatives tied to nonregulated underlying assets or variables, such as certain commodities. Foreign brokers, advisors, and fund managers can now facilitate a broader range of hedging and risk management instruments without triggering FBA licensing requirements. Derivatives traded outside a derivatives exchange, or over the counter (OTC), whose payments are calculated by reference to foreign exchange rates or interest rates. This removes an FBA licensing barrier for foreign providers of widely used OTC hedging products, broadening the solutions available to importers and exporters managing currency exposure and to borrowers seeking greater certainty over financing costs. The ministerial regulations also exempt brokers and agents handling transactions involving either of these two derivatives categories. For securities businesses, the ministerial regulations add exemptions for margin loans used to purchase securities and for securities repurchase transactions. These additions clarify whether such activities qualify as exempt brokerage
September 4, 2026
Foreign business restrictions on telecommunications, treasury center businesses, and intragroup support services were eased when Thailand published the Ministerial Regulation Prescribing Service Businesses Not Requiring Permission for Foreign Business Operations (No. 5) B.E. 2569 (2026) in the Government Gazette on August 28, 2026. The ministerial regulation expands the categories of service businesses that foreign investors may operate without a foreign business license (FBL) under the Foreign Business Act B.E. 2542 (1999) (FBA). Of particular relevance to the telecommunications, fintech, and technology sectors, the ministerial regulation exempts: Type 1 telecommunications licensees, which do not have their own networks; Treasury center businesses operated in accordance with Thailand’s exchange control regulations; and Certain intragroup administrative, human resources, and information technology management services. Telecommunications Services Foreign-owned businesses providing telecommunications services under a type 1 telecommunications license may now operate without obtaining an FBL. This may streamline market entry for qualifying telecommunications and digital infrastructure businesses. The exemption applies only to the FBA licensing requirement. Operators must continue to comply with applicable requirements under the Telecommunications Business Act and the regulations of the National Broadcasting and Telecommunications Commission, and the change does not affect foreign ownership restrictions applicable to type 2 or type 3 telecommunications businesses. Treasury Center Businesses The ministerial regulation also exempts qualifying treasury center businesses from the FBL requirement. This may facilitate centralized treasury functions in Thailand, including liquidity management, foreign exchange management, and intragroup funding arrangements. Treasury center operations remain subject to applicable requirements of the Bank of Thailand and other competent authorities. Intragroup Administrative, HR, and IT Services Certain administrative, human resources, and information technology management services provided between affiliated entities are also exempt, provided the relevant entities satisfy prescribed ownership or management criteria. The exemption is available where the service provider and recipient are related through specified ownership