
You are using an outdated browser and your browsing experience will not be optimal. Please update to the latest version of Microsoft Edge, Google Chrome or Mozilla Firefox. Install Microsoft Edge

December 30, 2022

Thailand Preparing to Tax Securities Transactions

Thailand’s cabinet has approved draft legislation to impose a financial transactions tax (FTT) on securities trading in the Stock Exchange of Thailand (SET). The cabinet’s decision, which came on November 29, 2022, sets Thailand on a path to repeal a tax exemption that has been in place for over 30 years. If the legislation is ultimately passed, the FTT will be applied to transactions starting in April 2023.

The sale of securities on the SET has been exempt from specific business tax (SBT) since December 1991 in an effort to promote trading on the secondary market and boost the domestic economy. The draft legislation approved by the cabinet in November 2022 aims to repeal the SBT exemption on securities trading on the SET and impose an FTT, which is a kind of SBT imposed on a specific commercial transaction. It is an indirect and transactional tax (similar to a sales tax) and is imposed on gross receipts, not on value added at each stage of manufacturing, trading, or service like VAT.

Generally, securities sellers are the ones liable for FTT. However, the draft law stipulates that securities brokers are to withhold FTT from the gross share sales income and remit it to the Revenue Department on behalf of the securities seller within the 15th (or 23rd, depending on circumstances) day of the next month through the Revenue Department’s e-filing platform. Under this arrangement, securities sellers and investors do not have any duty to remit SBT, and sellers have no reporting obligations regarding sale transactions.

Under the current draft, the imposition of FTT will be implemented in two phases, with an initial reduced rate as detailed in the table below.
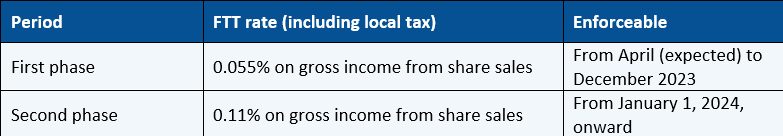
The securities subject to FTT include shares (both ordinary and preference), warrants, derivative warrants, exchange traded funds, depositary receipts, mutual fund units, and transferable subscription rights. Exempted persons include registered market makers, the Social Security Office, provident funds, the Government Pension Fund, aid funds under the Private School Act, retirement mutual funds, and the National Savings Fund, among others.

Securities traders may be subject to other tax implications besides FTT, such as capital gains tax and stamp duty, if a security is traded outside the SET. However, Thai and foreign individual investors can still be exempted from personal income tax on capital gains. Domestic companies may be subject to a capital gain at the prevailing rate of 20%, and foreign companies may be subject to 15% withholding tax on gains from a sale if payment is made from or in Thailand—though this rate may be reduced or exempted under the relevant Double Tax Agreements.

For more information on Thailand’s security-related tax requirements, or on any aspect of taxation in Thailand, please contact Auaychai Sukawong at [email protected].
 

RELATED INSIGHTS​ 

September 9, 2026
Certain securities, derivatives, and treasury activities in Thailand were opened to foreign investors when Thailand’s Ministry of Commerce published two new ministerial regulations in the Government Gazette on August 28, 2026. The regulations significantly broaden the service activities that foreign-owned businesses may conduct without a license or certificate under the Foreign Business Act B.E. 2542, as amended (FBA). Securities and Derivatives Business Exemptions Prior to the issuance of these ministerial regulations, the exemptions covered (1) securities brokerage and derivatives brokerage with their only underlying assets being agricultural commodities, financial instruments, and securities; and (2) dealers, advisers, and fund managers conducting derivatives business under Thailand’s derivatives laws. The ministerial regulations provide broader exemptions. In addition to derivatives under the laws on derivatives as before, the following two major categories are provided: Derivatives whose underlying assets or variables fall outside the scope of Thailand’s laws on derivatives. This addresses a gap in the previous framework, which did not comprehensively exempt derivatives tied to nonregulated underlying assets or variables, such as certain commodities. Foreign brokers, advisors, and fund managers can now facilitate a broader range of hedging and risk management instruments without triggering FBA licensing requirements. Derivatives traded outside a derivatives exchange, or over the counter (OTC), whose payments are calculated by reference to foreign exchange rates or interest rates. This removes an FBA licensing barrier for foreign providers of widely used OTC hedging products, broadening the solutions available to importers and exporters managing currency exposure and to borrowers seeking greater certainty over financing costs. The ministerial regulations also exempt brokers and agents handling transactions involving either of these two derivatives categories. For securities businesses, the ministerial regulations add exemptions for margin loans used to purchase securities and for securities repurchase transactions. These additions clarify whether such activities qualify as exempt brokerage
September 2, 2026
On August 21, 2026, Thailand’s Securities and Exchange Commission (SEC) published two consultation papers that would broaden regulated access to crypto assets while tightening custody standards. The first proposes a framework for establishing crypto exchange-traded funds (crypto ETFs) in Thailand. The second proposes enhanced qualification requirements for foreign digital asset custodians serving mutual funds and private funds that invest in digital assets. The proposals seek to expand regulated access to crypto assets while strengthening custody, governance, disclosure, and investor protection, and they affect fund managers, trustees, and licensed digital asset operators. Comments on both papers are due by September 20, 2026, and the SEC expects the resulting rules to take effect later in 2026. Elevating Foreign Custodian Standards Under current rules in effect since January 16, 2025, mutual funds and private funds investing in digital assets may use foreign custodians that meet qualifications similar to those set for domestic digital asset business operators. The SEC now proposes that foreign digital asset custodians satisfy two cumulative requirements: Compliance with the existing baseline qualifications: demonstrated expertise, robust cybersecurity measures, segregation of client assets, controls preventing unauthorized asset transfers, and sound financial standing. Supervision by a regulator that is either (1) an IOSCO Signatory A member under the Multilateral Memorandum of Understanding, the international arrangement through which securities regulators share information and cooperate on enforcement, or (2) a regulator in a jurisdiction that the Thai SEC designates as having adequate supervisory and investor protection standards. The SEC is initially considering 11 jurisdictions for the approved-country list: France, Germany, Hong Kong SAR, Ireland, Japan, Liechtenstein, Luxembourg, Malaysia, Singapore, South Korea, and the United States. The SEC may expand this list over time based on its assessment of other jurisdictions’ regulatory frameworks governing custodian licensing, asset segregation, secure custody practices, client rights in insolvency,
August 20, 2026
As part of its membership in Lex Mundi, Tilleke & Gibbins has released the latest edition of its Guide to Doing Business in Thailand, providing an overview of the legal, regulatory, and commercial considerations for companies establishing or expanding operations in Thailand. The 2026 edition offers practical insight into the country’s business environment, investment framework, and operational requirements. The guide covers a wide range of topics relevant to foreign and domestic investors, including: Investment incentives and promotion schemes Financial facilities and banking regulations Exchange controls and money transfers Import and export regulations Business structures and incorporation options Requirements for establishing a business Operational and compliance considerations Business cessation and insolvency procedures Employment and labor laws Taxation Immigration and visa requirements Prepared by Tilleke & Gibbins lawyers across multiple practice areas, the publication outlines key aspects of doing business in Thailand, including foreign investment restrictions, regulatory compliance obligations, corporate structures, employment requirements, and recent legal and economic developments affecting investors. The publication forms part of Lex Mundi’s Country Guides series, a global collection of jurisdiction-specific reference materials prepared by member firms around the world. Together, these guides help companies evaluate opportunities, compare regulatory environments, and plan international business activities across multiple markets. The full Guide to Doing Business in Thailand 2026 is available through the button below.
August 6, 2026
Every month, VAT-registered businesses in Thailand calculate their output and input VAT and file a return to pay the net amount due or claim a refund. Yet a common and costly dispute arises when a business that has paid input VAT to its supplier—and done everything asked of it—later finds that input VAT rejected on the grounds that the tax invoice was issued by “a person not entitled to issue tax invoices.” In these cases, a buyer may have confirmed the supplier’s VAT registration on the Revenue Department’s website, paid through the banking system, received a complete tax invoice, and kept full payment and inventory records. Even so, if the Revenue Department later determines that the supplier did not genuinely make the sale or collected the VAT without remitting it, the department can disallow the input VAT and assess additional tax, surcharge, and penalty—often more than a year after the transaction. A new article from tax and dispute resolution specialists at Tilleke & Gibbins in Bangkok examines how the Revenue Department and the courts approach these disputes, including two recent Supreme Court (Tax Division) decisions confirming that the taxpayer bears the burden of proving a supplier genuinely sold and delivered the goods and received payment. It considers why the VAT registration system offers no legal safe harbor, why the evidentiary burden falls hardest on online and cross-border transactions where buyers and sellers never meet, and how the Revenue Department’s own digital infrastructure could detect non-remitting suppliers at the source rather than shifting the loss to good-faith buyers. The article also sets out practical guidance: how to build a comprehensive “know-your-supplier” file at the time of a transaction, the procedural steps and strict deadlines for challenging a VAT assessment, and why dispute readiness belongs alongside tax planning at the center