
You are using an outdated browser and your browsing experience will not be optimal. Please update to the latest version of Microsoft Edge, Google Chrome or Mozilla Firefox. Install Microsoft Edge

May 19, 2020

Reinsurance Revolution in Myanmar

On May 12, 2020, Myanmar’s Insurance Business Regulatory Board (IBRB) issued Directive 4/2020—a game-changer for the insurance industry in Myanmar. Previously, reinsurance in Myanmar had only been available through the state-owned Myanma Insurance, without competition. However, when this directive comes into force on October 1, 2020, insurance companies (or cedants) will be able to obtain reinsurance from other insurers or reinsurers within Myanmar or abroad, with certain restrictions.

Reinsurance (and retrocession—the insurance or reinsurance of reinsurers) is a critical part of the insurance industry because it allows insurance companies to spread their risk and remain solvent in the event of large claims. It is expected that this new directive will result in Myanmar insurers—already undergoing tectonic shifts following the introduction of five foreign life insurer licenses and six foreign-Myanmar insurance joint ventures—seeking substantial reinsurance outside Myanmar. This greater spreading of insurance risk is a very positive development for the insurance market in Myanmar.

Reinsurance and Risk Retention

Under the directive, every insurer in Myanmar must retain risk up to the maximum amount commensurate with its financial strength, and must formulate a suitable retention policy for each insurance segment. In the case of life insurers and reinsurers transacting life insurance business, that must be a minimum of 20% of the sum at risk.

Every Myanmar insurer must also formulate a reinsurance program and retention policy and submit it to the IBRB at the beginning of each financial year.

Reinsurers and Licensing

Any reinsurer who wishes to operate within Myanmar must have a reinsurance license from the IBRB.

Foreign reinsurers or cross-border reinsurers who do not have a license to conduct insurance business in Myanmar will now also be permitted, subject to the following conditions:

  • They must have been licensed in their home country for at least the past three continuous years;
  • They must have a credit rating of at least BBB from S&P or equivalent for at least the past three continuous years;
  • They must have maintained a minimum solvency margin or capital adequacy as specified by their home country regulator for at least the past three continuous years;
  • Their past claims settlement must be satisfactory to the IBRB; and
  • They must comply with other requirements that may be stipulated by the IBRB.

Engaging a Reinsurer

Other than for life insurance, insurers must offer the best terms obtained to reinsurers in the following order:

  1. Myanma Insurance;
  2. Myanmar reinsurers or foreign reinsurers with representative offices in Myanmar; and
  3. Foreign reinsurers.

Insurers are obliged to follow this order of priority only if the terms offered are equaled (or bettered).

Again, other than life insurance, the IBRB has placed the following limits on cession to foreign reinsurers:
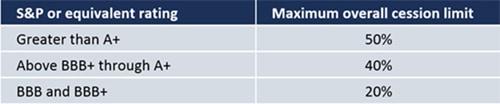
However, there is one catch that may prove frustrating. Section 20 of the directive provides that every Myanmar insurer, Myanmar reinsurer, and foreign reinsurer must cede a compulsory maximum of 10% of any insurance segment business to Myanma Insurance. Myanma Insurance is free to accept or reject the cession and will presumably be able to impose upon it such terms as it sees fit. Only if Myanma Insurance fails to offer such reinsurance is the insurer free to obtain cross border reinsurance from a foreign reinsurer for that original 10%. It seems probable that this provision will have a negative effect, because it will likely result in insurers being forced to comply with uncommercial terms from Myanma Insurance, despite better terms being available in Myanmar or abroad.

Insurance Pools

Insurance pools are another method by which smaller insurance companies can share risk. Insurance pools may now be formed in Myanmar, subject to a proposal being made to and approved by the IBRB.

Conclusion

Despite what some may see as the unwelcome involvement of Myanma Insurance, this directive is undoubtedly a giant step forward in the further liberalization and spreading of risk within the Myanmar insurance market, and is likely to herald large changes in reinsurance and retrocession both inside Myanmar and beyond.

For more information on this development, or on any aspect of doing business in Myanmar, please contact Tilleke & Gibbins’ Yangon office on [email protected]

RELATED INSIGHTS​ 

August 20, 2026
As part of its membership in Lex Mundi, Tilleke & Gibbins has released the latest edition of its Guide to Doing Business in Thailand, providing an overview of the legal, regulatory, and commercial considerations for companies establishing or expanding operations in Thailand. The 2026 edition offers practical insight into the country’s business environment, investment framework, and operational requirements. The guide covers a wide range of topics relevant to foreign and domestic investors, including: Investment incentives and promotion schemes Financial facilities and banking regulations Exchange controls and money transfers Import and export regulations Business structures and incorporation options Requirements for establishing a business Operational and compliance considerations Business cessation and insolvency procedures Employment and labor laws Taxation Immigration and visa requirements Prepared by Tilleke & Gibbins lawyers across multiple practice areas, the publication outlines key aspects of doing business in Thailand, including foreign investment restrictions, regulatory compliance obligations, corporate structures, employment requirements, and recent legal and economic developments affecting investors. The publication forms part of Lex Mundi’s Country Guides series, a global collection of jurisdiction-specific reference materials prepared by member firms around the world. Together, these guides help companies evaluate opportunities, compare regulatory environments, and plan international business activities across multiple markets. The full Guide to Doing Business in Thailand 2026 is available through the button below.
August 14, 2026
Thailand’s Office of the Insurance Commission (OIC) has issued guidelines clarifying the boundaries between permissible and prohibited activities for unlicensed individuals—including influencers, bloggers, and content creators—when communicating about insurance products on social media. The Good Practice Guidelines for Persons Not Licensed as Insurance Agents or Brokers Regarding the Dissemination of Insurance Content Through Digital Media B.E. 2569 (2026) took effect on July 24, 2026. Activities Requiring a License The guidelines reserve the following activities for licensed agents and brokers: Soliciting or facilitating insurance contracts. Providing personalized advice on product suitability. Recommending policy cancellation to purchase promoted products. Creating links that facilitate contract formation. Receiving performance-based compensation tied to policies or premiums generated. Importantly, boilerplate disclaimers such as “this is not a recommendation to buy insurance” will not shield individuals from liability if the OIC views the content as personalized advice or solicitation. Permitted Activities Unlicensed persons may present general educational content about insurance—such as explaining terminology, sharing industry statistics, reporting news, or sharing personal experiences—provided the content does not target specific individuals to purchase from specific companies. The guidelines also set out best practices for communication, including presenting information in a fair and balanced manner that covers both benefits and limitations, encouraging consumers to read policy terms and consult licensed professionals, verifying information from credible sources before dissemination, and exercising special care when the audience may include vulnerable groups such as persons aged 60 and older. Prohibited Practices Prohibited practices include fear-based marketing, creating artificial urgency, omitting material limitations, making exaggerated claims, falsely claiming professional credentials, using fake engagement mechanisms, and sharing false or misleading content. The guidelines also reinforce the prohibitions under section 83 of the Life Insurance Act B.E. 2535 and section 78 of the Non-Life Insurance Act B.E. 2535 against soliciting insurance contracts with foreign operators
June 30, 2026
Tilleke & Gibbins’ insurance specialists in Bangkok provided Thomson Reuters’ latest country update on Thailand’s regulatory framework for the insurance industry. The country update, which is part of Thomson Reuters’ extensive Regulatory Intelligence offerings, contains information and guidance for insurers active in the Thai market. The guide covers the following topics in detail: Permission to operate; Legal and regulatory considerations for domestic and international insurers; Capital reserve requirements; Investment management and markets; The Office of Insurance Commission’s arbitration system for handling complaints; Creditor hierarchy; Rehabilitation of non-life insurance companies; and Personal data protection requirements for insurers. Thomson Reuters Regulatory Intelligence is a service that provides with curated news, analysis, and data across jurisdictions to help legal, risk, and compliance professionals manage compliance and mitigate global risk. The full Thailand insurance country update is available by subscription to Regulatory Intelligence on the Thomson Reuters website.
June 30, 2026
Insurance specialists from Tilleke & Gibbins have provided an update to the Vietnam chapter of Thomson Reuters’ Practical Law guide to insurance and reinsurance. The guide is a Q&A-style overview of insurance and reinsurance law in jurisdictions worldwide. The Vietnam chapter provides a detailed overview of the legal framework for the insurance and reinsurance market in the country, covering the following issues: Regulatory framework for insurance and reinsurance Authorization for insurers, reinsurers, and insurance intermediaries Ownership restrictions Ongoing requirements Penalties for noncompliance Sales and marketing of insurance and reinsurance Transfer of risk Reinsurance contracts and risks Contracts and policies Claims Dispute resolution Insolvency Tax Practical Law, a legal reference resource from Thomson Reuters, publishes a range of guides for hundreds of jurisdictions and practice areas. The insurance and reinsurance guide is a valuable resource for legal practitioners, covering numerous jurisdictions worldwide. To view the latest version of the guide, please visit the Practical Law website and enroll in the free Practical Law trial to gain full access.